

Fiscalité des résidents américains : carte verte ou présence substantielle
Santos Lloyd Law Team • March 28, 2024

Click here to read this article in English
ISi vous êtes un résident américain au sens de la section 7701(b)(1)(A) de l'Internal Revenue Code (IRC), un immigrant doit comprendre les obligations fiscales américaines.
Lorsque vous êtes résident permanent, vos revenus mondiaux sont soumis à l’impôt sur le revenu américain de la même manière qu’un citoyen américain.
Vous êtes un résident fiscal des États-Unis si vous remplissez soit le test de la carte verte, soit le test de présence substantielle
pour l’année civile.
1. Le test « Carte verte » signifie que vous possédez une carte de résident permanent, formulaire I-551, également connue sous le nom de « carte verte », à tout moment de l'année civile.
- Vous continuez à avoir le statut de résident américain, sauf si : vous renoncez et abandonnez volontairement votre statut de résident, ou votre statut de résident prend fin, soit par l'USCIS, soit par un tribunal fédéral américain.
Si vous remplissez le test de la carte verte à tout moment au cours de l'année civile, mais ne remplissez pas le test de présence substantielle pour cette année-là, la date de début de votre résidence est le premier jour où vous êtes présent aux États-Unis en tant que résident permanent légal. Autrement dit, si vous possédez votre carte verte depuis moins d’une année civile complète, vos obligations fiscales pourraient être moindres et sont calculées comme suit:
2. Afin de satisfaire au test de présence substantielle, vous devez être physiquement présent aux États-Unis au moins:
- 31 jours au cours de l'année en cours, et
- 183 jours pendant la période de 3 ans qui comprend l'année en cours et les 2 années immédiatement antérieures, en comptant:
a. Tous les jours où vous avez été présent dans l'année en cours, et
b. 1/3 des jours de présence la première année précédant l'année en cours, et
c. 1/6 des jours de présence la deuxième année précédant l'année en cours.
En d’autres termes, un examen rétrospectif s’applique lors du calcul du critère de présence substantielle aux fins fiscales américaines. Si un titulaire de carte verte ne satisfait pas à un critère de présence substantiel, il est alors soumis à l'impôt sur le revenu américain de la même manière qu'un citoyen américain MAIS SEULEMENT pour une partie de l'année civile, à compter de la date à laquelle il devient résident permanent des États-Unis.
Naviguer dans les complexités des lois américaines sur l’immigration et la fiscalité nécessite souvent des conseils juridiques professionnels. Demander l'aide d'un avocat spécialisé en droit de l'immigration et connaissant bien la fiscalité américaine peut améliorer considérablement les chances de réussite de votre planification en matière d'immigration, en garantissant le respect de ces réglementations et exigences complexes.
Si vous avez des questions sur ce que cela signifie pour vous, n'hésitez pas à prendre rendez-vous avec notre cabinet.
Nous nous ferons un plaisir de travailler avec vous!
Ce blog n'est pas destiné à fournir des conseils juridiques et rien ici ne doit être interprété comme établissant une relation avocat-client. Veuillez prendre rendez-vous avec un avocat spécialisé en droit de l'immigration avant d'agir sur la base de toute information lue ici.
This Facebook widget is no longer supported.
An artist receives an invitation to join a new production. A business professional is offered a consulting role alongside an existing position. A musician wants to perform for several organizers during the same season. For professionals whose careers involve multiple projects, an important immigration question often follows: can an O-1B visa cover work for more than one employer? The answer can be yes, but the employment arrangements must be covered by the appropriate petition structure. An O-1B approval does not provide unrestricted permission to accept any job in the United States. Your approved work arrangements matter The O-1B category allows qualifying individuals with extraordinary ability or achievement to work in their area of expertise. However, eligibility based on professional accomplishments is only part of the case. The petition must also establish the proposed work and the relationship between the professional and the petitioner. Before accepting an additional position, your attorney should review who filed the existing petition, the work it covers, and how the proposed opportunity fits into that arrangement. A valid visa and an unexpired approval notice do not answer those questions on their own. Separate employers or an agent petition When an O-1B beneficiary works for multiple employers during the same period, each employer generally files a separate petition unless an established U.S. agent files a petition covering the arrangement. An agent petition can be useful when a professional’s work involves several employers or engagements. Depending on the arrangement, the agent may act as an actual employer as well or only represent the employers and the professional. The petition must document the agent’s role and the proposed employment. For an agent petition involving multiple employers, the supporting documents include contracts and an itinerary identifying the engagements, their dates, the actual employers, and the locations where services will be performed. Your attorney will determine the documentation needed for your particular structure. A new opportunity may require another filing If you change employers while in the United States, a new petition is generally required. When the original case was filed through an agent, an amended petition may be necessary to address the new employer. Material changes to the approved employment terms can also require an amendment. There is a specific provision allowing petitioners for artists and entertainers to add qualifying performances or engagements during the petition’s validity without an amended petition. That flexibility should not be treated as blanket permission to change employers or accept unrelated work. Your attorney should assess whether it applies to the proposed engagement. Review the opportunity before agreeing to a start date A promising offer can come with a short deadline. Sharing the proposed contract, duties, employer information, and anticipated dates with your attorney early can help clarify the immigration requirements before business commitments are made. Your attorney will confirm whether the work is already covered, whether another petition is needed, and when you may begin. Do not assume that submitting a new petition automatically authorizes work for the new employer. Contact Santos Lloyd Law Firm, P.C. If you believe you may qualify for the O-1B status and to discuss a filing strategy that fits your professional plans.
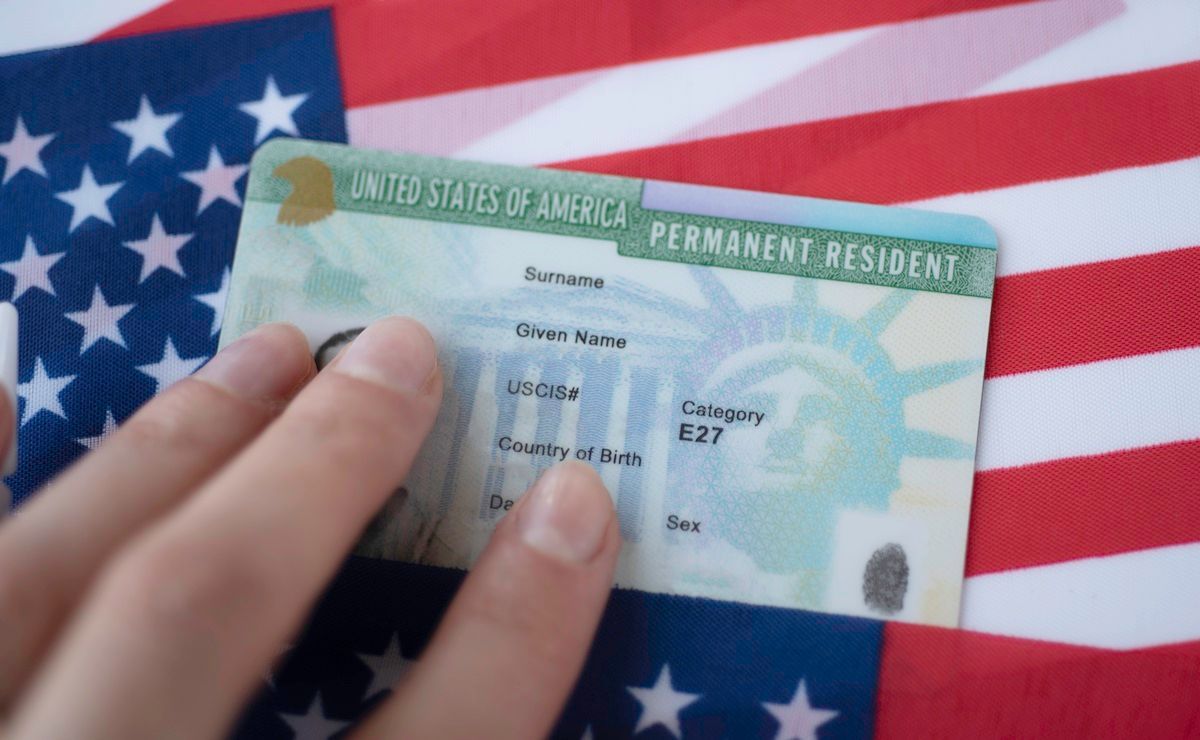
Receiving a two-year green card through marriage is an important step, but it leaves another process ahead: removing the conditions on permanent residence. For couples preparing a joint Form I-751 petition, understanding the filing window and organizing evidence early can make the preparation more manageable. The starting point is your own record. Locate the green card, the notice granting residence, and copies of the earlier immigration filing. Check the date conditional residence began and the card’s expiration date. Do not calculate the next deadline solely from your wedding anniversary or the date an attorney first submitted your case. Understand the joint filing window Under 8 CFR 216.4 , a joint I-751 petition generally must be filed during the 90-day period immediately before the second anniversary of obtaining conditional permanent residence. This is a window before that anniversary, not an additional 90 days after the card expires. Preparing early and filing early are different things. You can begin gathering records well before the window opens, while coordinating the correct submission date with your attorney. A joint petition also requires the appropriate signatures, fee, and supporting documentation. Confirm the current form instructions, accepted filing method, and applicable fee when the case is ready to submit. Build a record of the marriage over time The regulation identifies several types of evidence that may help show the marriage was not entered into to evade immigration law: jointly owned property, a lease for a shared home, combined financial resources, children’s birth certificates, and statements from people with personal knowledge of the relationship. These examples do not mean every couple must have a mortgage, joint accounts, or children. The evidence should accurately reflect your circumstances. A clear explanation of how you manage your household can be more useful than forcing your relationship into a checklist that does not fit. As a practical preparation step, organize records by date and type. Review whether they help explain the course of the marriage, rather than collecting only documents created shortly before filing. Flag separate addresses, name changes, or gaps in the records for your attorney. Never alter a document to make the history appear simpler. Tell your attorney if circumstances change This article addresses joint filing. Divorce, the death of a spouse, abuse, or other significant changes may require a different filing basis or an individualized assessment. Separate waiver provisions exist, with their own requirements. A spouse’s unwillingness to sign does not, by itself, establish eligibility for every waiver. Do not assume that the joint 90-day window answers every question about a non-joint case. If the relationship changes while preparing the petition or while it is pending, inform counsel promptly. You should not need to invent a continuing relationship to seek advice about the options that may actually apply. Keep tracking the case after submission The regulation provides that conditional resident status is automatically extended, when necessary, upon receipt of a properly filed I-751 until adjudication. Proof of that status is a separate practical matter: keep the receipt notice and have counsel review its wording before relying on it for travel or employment documentation. This article does not promise a particular receipt-extension period or processing time. A missed deadline calls for prompt legal attention. The regulation allows some late joint filings where USCIS accepts a written showing of good cause, but acceptance is not automatic. Do not assume a late petition cures the problem without further review. Santos Lloyd Law Firm, P.C. can help you assess the filing window, organize relevant evidence, and identify changes that may affect your I-751 strategy. Contact the firm early enough to review the facts before the deadline approaches.
October begins a new federal fiscal year, but that does not mean every green card applicant moves to the front of the line. The Department of State’s October 2026 Visa Bulletin sets out the visa availability that applicants in family-sponsored and employment-based preference categories need to review this month.
